Home · Costs & Insurance
What roofing costs in the Magnolia area, and how the money works
How much does roof repair or replacement cost in the Magnolia area, and does insurance cover it?
Most full replacements in the Magnolia area land between about $10,000 and $20,000 in published national guides for an architectural shingle system on a typical home, with metal on acreage priced higher against a far longer life, while component repairs, a boot, a flashing run, a valley rebuild, run from about $400 to about $2,000 by the part. Whether insurance helps depends on cause, not cost: a dated storm event that lifted shingles or dropped a limb is claim territory, with photographs taken before anyone cleans up, while a first-generation builder roof simply wearing out under the pines is the owner's purchase. The covered ZIPs serve about 71,000 postal residents around a small city proper. Around Magnolia the honest scope says which of those two stories your roof is telling, in writing, before a deposit is discussed.
Three kinds of roofing bills come out of the piney woods, and they should never arrive blended. A component bill names a part and an hour count. A storm bill follows a dated photo set line by line. A replacement bill prices a whole system, and on the acreage lots a metal system gets priced against the decades it will serve, not the week it takes to stand up. The published guide bands below frame all three. What you sign should say which kind of bill it is, list its materials, and carry the shingle wind rating and algae line where a system is being sold.
Compiled from published national guides and local data; reviewed by the Caney Creek Roofing Co research team. Last reviewed November 16, 2026.
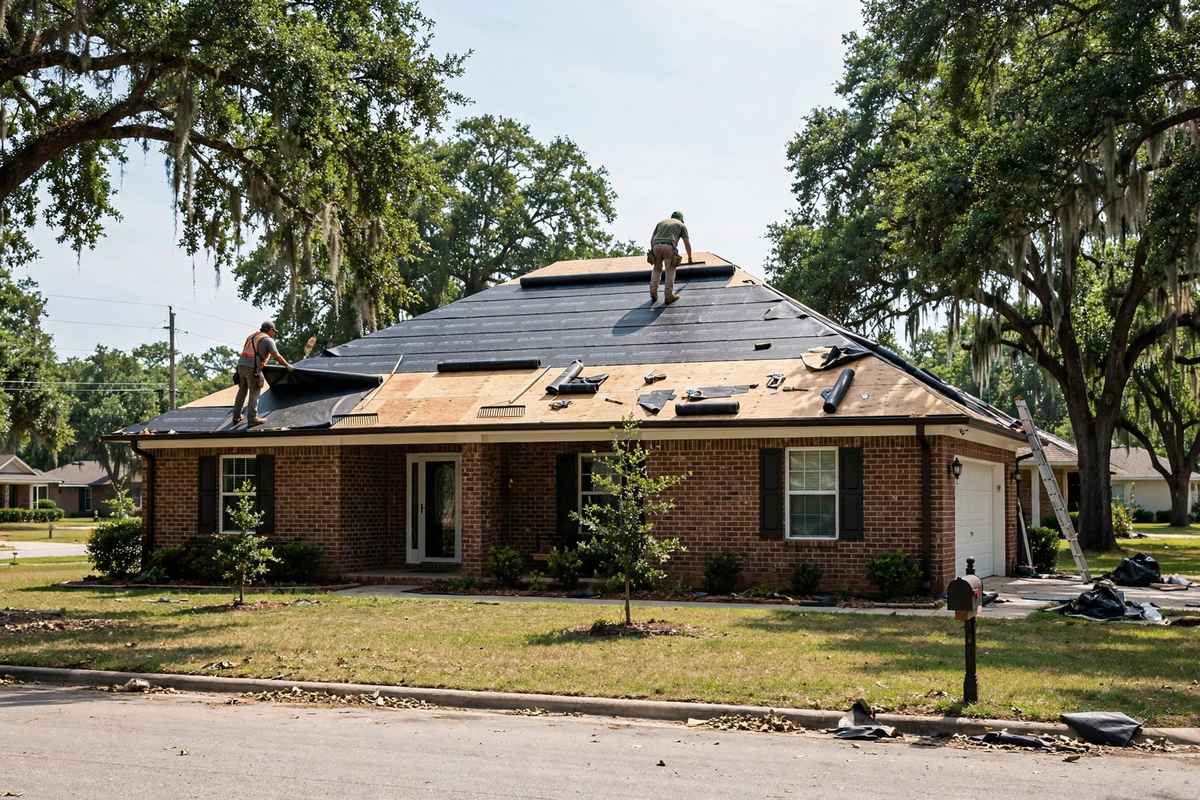
Typical cost ranges
| Job | Typical range | What moves it |
|---|---|---|
| Leak repair (boot, flashing or valley) | $400 to $1,800 | The entry point is found from the attic side where possible and photographed; the straw load found in the valleys is reported with the invoice. |
| Emergency tarping after a storm | $300 to $1,000 | Charged by the area covered and how it is anchored; the crew leaves a dated return visit for the full inspection on the invoice. |
| Storm damage repair (one slope or impact) | $1,200 to $5,000 | Built line by line off the dated photographs; any decking found rotten on opening is quoted as its own line before it is replaced. |
| Full replacement (shingle system) | $10,000 to $20,000 | Architectural shingles with the algae line standard under canopy; the price carries its wind rating, its venting correction and its warranty as named items, not footnotes. |
Guide bands frame the work; they are not a bid on your roof. The bid comes after the inspection, and in this footprint it should spell out the valley work, the decking allowance and the warranty in plain items a homeowner can check off as the job proceeds.
How insurance pays for this work
The deductible question
A storm policy answers events, not birthdays: wind that lifted a field last Tuesday is a claim, while a builder roof quietly reaching the end of a short life is a purchase. Read your wind deductible before filing anything small, because in this part of Texas it is commonly figured as a percentage of the home's insured value and can exceed a modest repair outright. Keep the dated photo set either way. Under these pines, last season's documentation is next season's proof of what the storm changed.
Request a callback
Prefer to talk later? Leave your details and an independent local pro will call you back. No charge to you, no obligation.
Caney Creek Roofing Co is a free referral service. Submitting this form connects you with independent local contractors who provide the work.